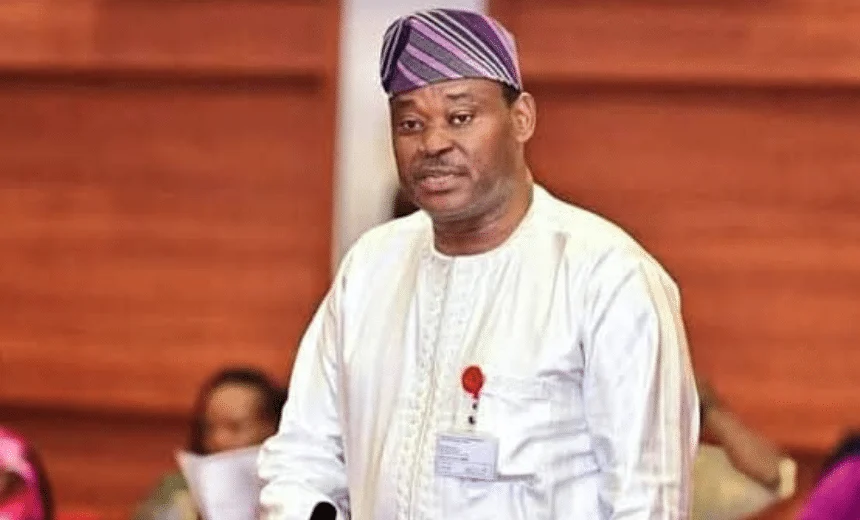
Sen. Jimoh Ibrahim says Nigeria’s absence from the world’s most indebted countries reflects disciplined fiscal coordination under President Bola Tinubu.
Ibrahim, who represents Ondo South and is an ambassador-designate, made the remarks in a statement Wednesday amid renewed debate over Nigeria’s debt profile and borrowing pattern.
His comments follow new global debt data released for the fourth quarter of 2025 by the Institute of International Finance in its Global Debt Monitor, analyzed by Visual Capitalist.The report shows several advanced economies with total debt exceeding 300% of gross domestic product.
Hong Kong ranked highest at 380% of GDP, followed by Japan (372%), Singapore (347%), France (326%) and Canada (315%). The figures include government, corporate and household debt.
Among African countries, Senegal (156%), South Africa (149%) and Tunisia (143%) show rising debt levels, largely driven by sovereign borrowing. Nigeria does not rank among the most indebted countries globally by total debt-to-GDP ratio and is not in Africa’s top 10.
Ibrahim said critics who predicted unsustainable borrowing under Tinubu had been mistaken.
“Those who expected reckless borrowing have been proven wrong,” he said. “Nigeria is not on the list of the world’s most indebted countries. This reflects deliberate fiscal coordination and structured economic reforms.”
He said the government’s fiscal outlook shows borrowing has remained within manageable limits and aligned with revenue reforms. He cited policies such as fuel subsidy removal and exchange rate unification as efforts to stabilize public finances and reduce long-term vulnerabilities.
Ibrahim also said Nigeria continues to access credit for infrastructure and development projects but within sustainable thresholds.
He described the trend as evidence that “Bolaeconometrics” — a term used by supporters to describe Tinubu’s economic recalibration — is yielding results.
However, he cautioned that Nigeria’s position outside the high-debt bracket does not eliminate fiscal risks.
“While Nigeria may not rank among the most indebted countries globally, the sustainability of its debt remains closely tied to revenue generation and debt servicing capacity,” he said.
He added that improving non-oil revenue, boosting exports and enhancing public sector efficiency will be critical to maintaining fiscal stability.
Nigeria’s public debt sustainability remains a subject of debate, especially amid global economic pressures, tighter monetary conditions and exchange rate volatility affecting emerging markets.
Still, Ibrahim expressed confidence that ongoing reforms will strengthen the country’s macroeconomic fundamentals.
“As reforms mature and revenue improves, Nigeria’s fiscal resilience will become even more evident,” he said.
He maintained that available global data support the view that Nigeria remains outside the world’s most heavily indebted nations, even as domestic debate over borrowing strategy continues.