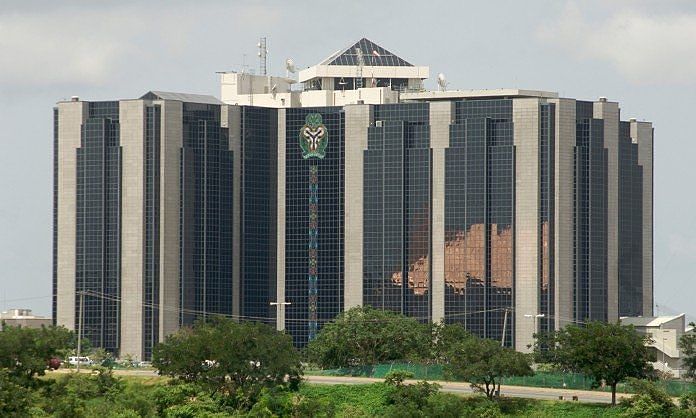
The Central Bank of Nigeria has given deposit money banks 18 months to comply with new baseline standards for automated anti-money laundering solutions, while other financial institutions have 24 months to meet the requirements.
In a circular dated March 10, 2026, the regulator said implementation of the guidelines begins immediately, with full compliance expected within the specified timelines.
“The implementation of these guidelines shall start from the date of issuance, while full compliance shall be 18 months for deposit money banks and 24 months for other financial institutions,” the bank said.
The circular, titled Issuance of Baseline Standards for Automated Anti-Money Laundering Solution for Financial Institutions in Nigeria, was signed by Akinwunmi Olubukola, director of the Banking Supervision Department, and Olubunmi Ayodele-Oni for the director of the Compliance Department.
It was addressed to banks, mobile money operators, international money transfer operators, payment service providers and other financial institutions.
The central bank also directed institutions to submit implementation road maps to its Compliance Department within three months of the circular.
The regulator said the standards are designed to strengthen financial system stability and integrity by improving systems used to combat money laundering, terrorism financing and proliferation financing.
The framework requires financial institutions to adopt automated tools capable of detecting and reporting suspicious transactions in real time while strengthening compliance with anti-money laundering and counter-terrorism financing regulations.
The CBN said all institutions under its supervision must operate automated AML solutions, though the complexity of each system will depend on the institution’s size, risk profile, business model, transaction volumes and operational complexity.
The guidelines are based on the Central Bank of Nigeria Act and the Banks and Other Financial Institutions Act and are intended to complement existing legal obligations.
The bank said manual controls alone are no longer sufficient as financial services become more digitized and complex.
Financial institutions are required to deploy systems that support risk-based customer due diligence, detect suspicious activities promptly and facilitate accurate reporting to regulators including the Nigerian Financial Intelligence Unit.
The standards also align with recommendations from the Financial Action Task Force and include requirements for transaction monitoring, know-your-customer and know-your-business processes, sanctions screening, fraud monitoring, reporting, audit trails and data security.
The framework encourages the use of artificial intelligence, machine learning and advanced analytics, subject to independent annual validation, accuracy checks and bias testing.
Institutions are also required to maintain tamper-proof audit trails, role-based access controls and secure authentication systems while complying with the Nigeria Data Protection Act.
The central bank said compliance will be monitored through off-site surveillance, on-site examinations and other supervisory reviews.
Failure to meet the standards could result in remedial directives, administrative sanctions and other penalties under existing laws.
“All stakeholders are required to ensure strict compliance with the guidelines,” the bank said, adding that it will continue to monitor developments and issue further guidance when necessary.