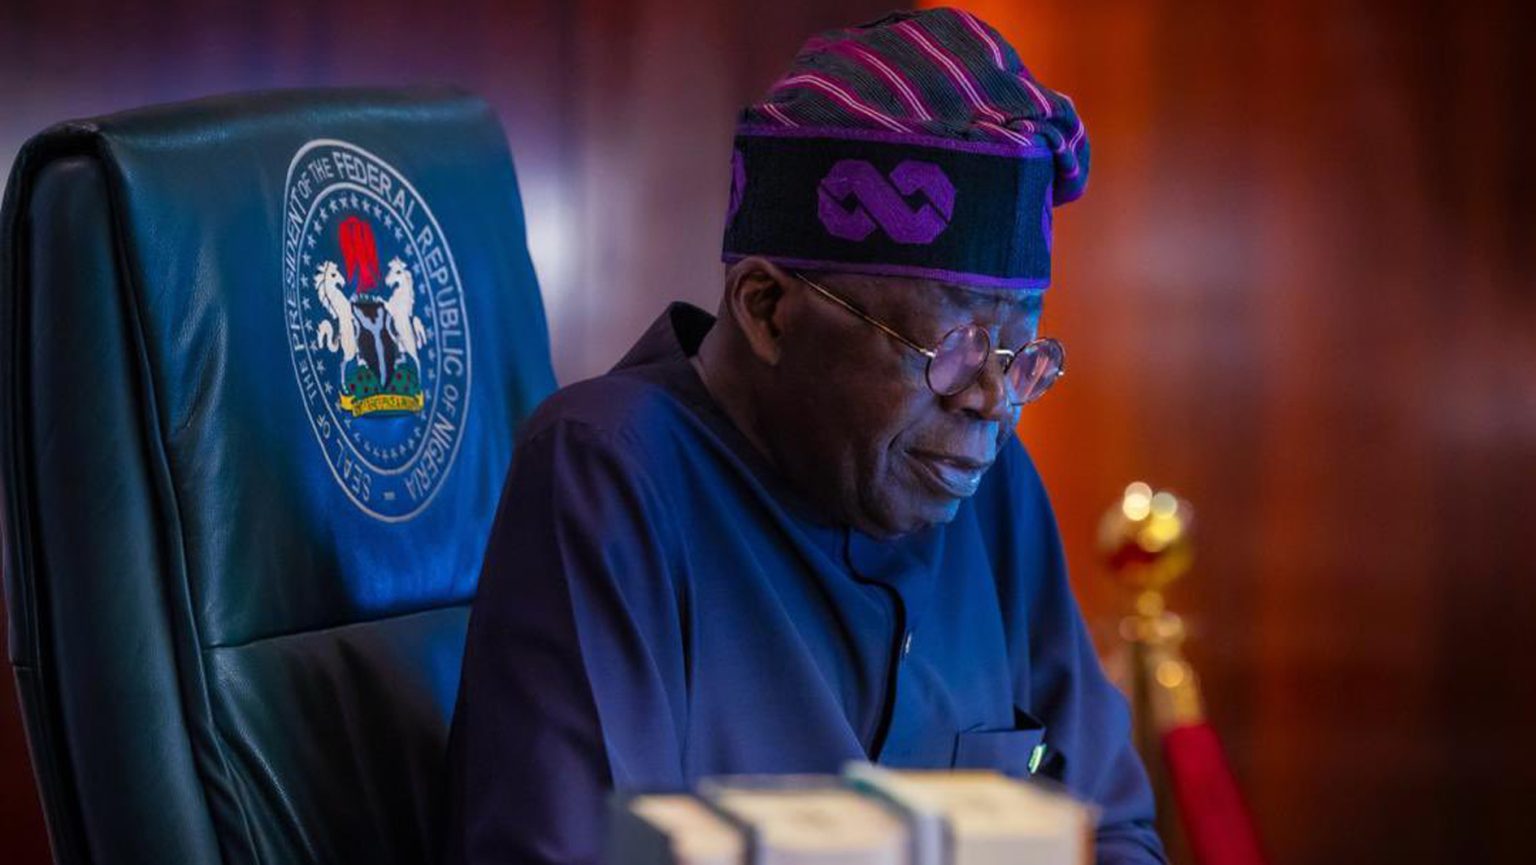
The Centre for the Promotion of Private Enterprise has said the first three years of President Bola Tinubu’s administration were largely devoted to restoring macroeconomic stability after inheriting significant fiscal, monetary and foreign exchange challenges, but noted that the benefits of the reforms have yet to translate into broad-based improvements in living standards.
In an assessment of the administration’s economic performance, CPPE Chief Executive Officer Dr. Muda Yusuf said the government assumed office amid severe foreign exchange illiquidity, multiple exchange rate windows, declining investor confidence and weakened external reserves.
According to Yusuf, fiscal conditions were also strained by extensive Ways and Means financing and a fuel subsidy regime that had become a major source of fiscal leakages and economic distortions.
He identified fuel subsidy removal and exchange rate unification as the two key reforms underpinning the administration’s economic stabilization agenda.
Yusuf said the removal of fuel subsidies eased pressure on public finances and laid the foundation for a more sustainable downstream petroleum sector, while exchange rate unification improved price discovery in the foreign exchange market and reduced arbitrage opportunities.
However, he noted that both reforms imposed significant adjustment costs on Nigerians.
“The immediate consequence of the reforms was a significant inflationary shock. Energy prices surged, transportation and logistics costs escalated, production expenses increased sharply, and the depreciation of the naira amplified imported inflation pressures,” Yusuf said.
He added that the reforms contributed to declining real incomes, worsening poverty levels and a prolonged cost-of-living crisis.
Despite these challenges, Yusuf said there were clear signs of macroeconomic recovery. He noted that external reserves had improved significantly, with gross reserves approaching $50 billion, while the balance of trade remained in surplus, investor confidence strengthened and exchange rate volatility moderated from 2025.
According to him, the economy recorded 11 consecutive months of disinflation from early 2025 through February 2026 before inflationary pressures resurfaced following the Iran-U.S.-Israel conflict in March 2026.
Yusuf also highlighted gains in the capital market, stating that the Nigerian Exchange All-Share Index rose from about 55,700 points in 2023 to more than 254,000 points in 2026, while market capitalization increased from approximately N30 trillion to more than N160 trillion.
He said the discontinuation of Ways and Means financing improved monetary discipline and macroeconomic stability, while the emergence of domestic refining capacity, led by the Dangote Refinery, strengthened foreign exchange conservation and energy security.
“An economy that produces more of what it consumes is inherently more resilient than one that depends excessively on imports,” Yusuf said.
Despite the progress, he identified elevated inflation, weak purchasing power and fragile consumer confidence as major unresolved challenges.
“The challenge before the administration is no longer merely one of economic stabilization; it is the imperative of converting reform gains into jobs, higher incomes, lower poverty and a better quality of life for Nigerians,” he said.
Yusuf also described insecurity as a major threat to economic recovery, citing its impact on agriculture, food production, rural livelihoods and investment.
“No economy can achieve food security when farmers face persistent threats to their lives and livelihoods,” he said.
He further identified high energy costs, logistics bottlenecks, policy inconsistency, inadequate infrastructure and elevated interest rates as factors constraining industrial competitiveness and job creation.
On fiscal sustainability, Yusuf said public debt rose to N159.3 trillion as of December 2025, driven partly by naira depreciation and the securitization of N23 trillion in legacy Ways and Means liabilities.
While noting that debt sustainability and fiscal space remain important policy concerns, he said ongoing tax reforms could strengthen government revenue and improve fiscal capacity.
Yusuf also emphasized the importance of governance, transparency and accountability in sustaining public support for economic reforms.
“The long-term sustainability of economic reforms rests on the principle of shared sacrifice. Public confidence is strengthened when citizens perceive that the costs of adjustment are borne not only by households and businesses, but also by the political and governing elite,” he said.
Looking ahead, Yusuf said the next phase of reforms should focus on translating macroeconomic stability into inclusive growth through stronger investment, improved productivity, enhanced energy security, food security, industrial competitiveness and poverty reduction.
“Ultimately, the success of the reform agenda will not be measured solely by reserve accumulation, exchange rate stability, or stock market performance. It will be judged by its impact on jobs, incomes, living standards and the quality of life of ordinary Nigerians,” he said.