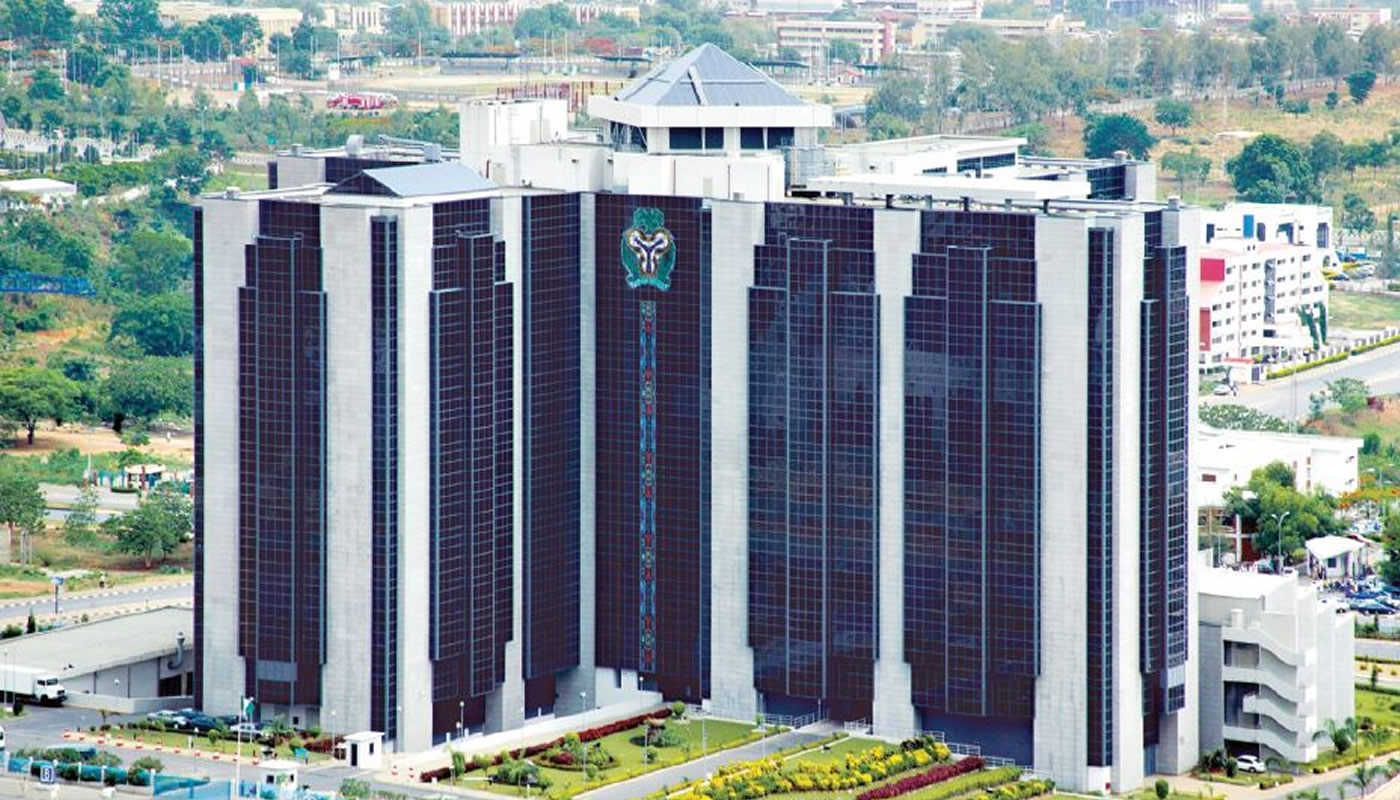
Nigeria’s banking sector recorded a rise in bad loans in January 2026, with the non-performing loan ratio climbing to 8.03%, according to the Central Bank of Nigeria’s January 2026 Economic Report.
The figure represents an increase from 7.51% recorded in December 2025 and remains above the CBN’s prudential threshold of 5%, signaling continued deterioration in asset quality across the banking industry.
The apex bank attributed the increase largely to the reclassification of loans following the withdrawal of regulatory forbearance granted to banks on certain credit exposures and single obligor limit breaches.
“Following the bank’s loan reclassification after the withdrawal of forbearance, the non-performing loans ratio rose by 0.52 percentage point to 8.03% compared with the level in the preceding period and was above the 5.00% prudential threshold,” the report stated.
In June 2025, the CBN directed banks benefiting from regulatory forbearance on credit exposures or single obligor limit waivers to suspend dividend payments, defer bonuses for directors and senior executives, and halt new investments in foreign subsidiaries and offshore ventures.
The regulator said the measures were designed to strengthen capital buffers, improve balance-sheet resilience and encourage banks to retain earnings while exiting temporary regulatory reliefs.
The apex bank also terminated COVID-19-related regulatory forbearance and waivers on single obligor limits effective June 30, 2025, requiring banks to align affected credit exposures with existing prudential guidelines.
The withdrawal of the relief measures resulted in the reclassification of previously restructured loans, many of which are now being recognized as non-performing, pushing the industry’s bad loan ratio above the regulatory ceiling.
The CBN warned in its macroeconomic outlook report that a significant increase in non-performing loans could weaken asset quality, impair bank balance sheets and pose systemic risks to the financial system.
To strengthen credit discipline and improve loan recovery, the regulator recommended broader integration of the Global Standing Instruction framework across financial institutions.
The CBN has also introduced a series of measures aimed at tightening risk management in the banking sector.
In February 2025, the bank ordered directors with non-performing insider-related loans to resign from their boards and directed financial institutions to recover such debts through collateral enforcement, including the seizure of affected directors’ shareholdings.
More recently, the regulator instructed banks to deny additional credit facilities and certain banking services to large borrowers with non-performing loans.
The directive, issued in March 2026 and signed by the Director of Banking Supervision, Dr. Muhammad Abdullahi, bars large-ticket obligors with non-performing facilities recorded in the Credit Risk Management System or licensed private credit bureaus from accessing new loans, letters of credit, performance bonds and other contingent liabilities.
According to the CBN, the restrictions are intended to reduce risks posed by large borrowers whose defaults could threaten financial system stability.
Despite concerns over rising bad loans, the central bank maintained that the banking system remains stable.
The report showed that the industry’s liquidity ratio increased to 63.38% in January from 57.22% in December, remaining well above the regulatory minimum of 30%.
Similarly, the capital adequacy ratio stood at 12.05% in January, slightly lower than the 12.35% recorded in December but still above the minimum requirement of 10%.
“The Nigerian banking industry remained resilient, with most financial soundness indicators staying within prudential regulatory thresholds, affirming financial stability and institutional soundness,” the CBN said.
Analysts said the figures present a mixed outlook for the banking sector. While liquidity and capital buffers remain strong, rising non-performing loans reflect pressure from legacy credit exposures, currency depreciation, elevated interest rates and stricter regulatory classifications.
The issue also drew attention from members of the Monetary Policy Committee during its February 2026 meeting.
CBN Deputy Governor for Economic Policy Dr. Muhammad Abdullahi described rising non-performing loans as a growing threat to financial stability and warned that they could weaken monetary policy transmission if not addressed.
“Additionally, rising NPLs could pose financial stability risks, and the broader macroeconomy needs to rebalance growth and stability objectives,” Abdullahi said.
MPC member Aku Odinkemelu also called for stronger regulatory oversight, saying the increase in bad loans underscores the need for heightened supervisory vigilance to protect asset quality and ensure effective credit transmission.
The comments highlight growing regulatory concern over loan quality as banks adjust to tighter prudential standards following the withdrawal of regulatory forbearance.